
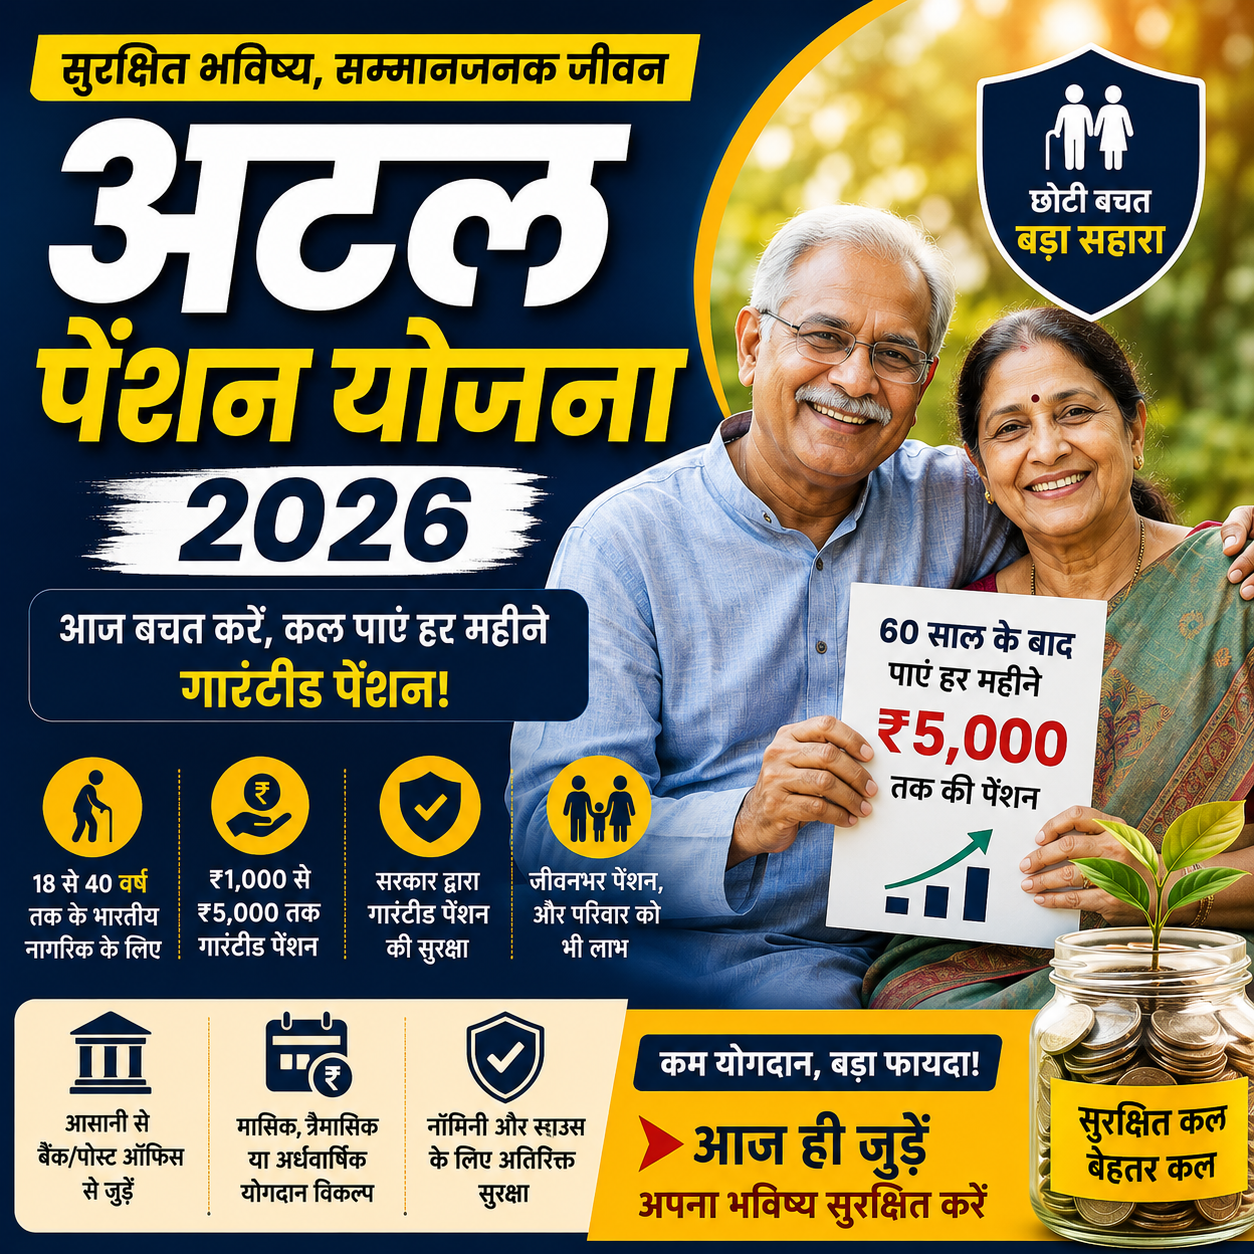
Atal Pension Yojana Scheme
Atal Pension Yojana 2026: Eligibility, Benefits, Contribution Chart, Online Apply, Pension Amount & Complete Details
Meta Title: Atal Pension Yojana 2026: Get ₹5,000 Monthly Pension After 60 Years
Meta Description: Learn everything about Atal Pension Yojana 2026, including eligibility, age limit, monthly contribution, ₹1,000–₹5,000 pension, online application, documents, withdrawal and benefits.
Suggested URL Slug: atal-pension-yojana-2026-online-apply-benefits
Primary Focus Keyword: Atal Pension Yojana 2026
Introduction: What Is Atal Pension Yojana 2026?
Planning for retirement is one of the most important financial decisions in everyone’s life. During our working years, we earn money to fulfil our family’s needs, manage household expenses, pay bills and build savings for the future. However, as people grow older, their ability to work and earn a regular income may gradually decrease.
For individuals working in the unorganised sector, retirement planning can become particularly challenging. Many workers do not receive a regular pension after retirement, making it difficult to maintain financial independence during old age.
To address this concern and encourage long-term retirement savings, the Government of India launched the Atal Pension Yojana (APY) on 9 May 2015. The scheme became operational from 1 June 2015 and is administered by the Pension Fund Regulatory and Development Authority (PFRDA).
Atal Pension Yojana is a government-backed, contribution-based pension scheme designed especially to encourage retirement savings among workers in the unorganised sector.
Under this scheme, eligible subscribers contribute a fixed amount regularly until they reach the age of 60 years. After completing the required contribution period, subscribers become eligible for a guaranteed minimum monthly pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000, depending on their selected pension slab.
One of the major advantages of this scheme is that the Government of India guarantees the minimum pension benefit according to the applicable scheme conditions.
In this detailed article, we will explain everything about Atal Pension Yojana 2026, including eligibility criteria, age limit, contribution chart, pension amount, online application process, required documents, withdrawal rules, spouse benefits and frequently asked questions.
Whether you are a private-sector employee, self-employed individual, shopkeeper, small business owner or worker in the unorganised sector, this guide will help you understand how APY works.
1. What Is Atal Pension Yojana (APY)?
Atal Pension Yojana is a voluntary pension scheme introduced by the Government of India to provide financial security to individuals during their old age.
The main objective of this scheme is to encourage people to save regularly during their working years so that they can receive a fixed monthly pension after attaining the age of 60.
Under APY, subscribers can choose one of five guaranteed minimum monthly pension options:
₹1,000 per month
₹2,000 per month
₹3,000 per month
₹4,000 per month
₹5,000 per month
The amount of contribution depends on three major factors:
The age at which a person joins the scheme.
The monthly pension amount selected.
The frequency of contribution.
People joining at a younger age generally need to contribute less because they have a longer period to save before reaching 60.
The scheme is particularly relevant for people who do not have access to a formal employer-sponsored pension.
Key Highlights of Atal Pension Yojana 2026
| Particular | Details |
|---|---|
| Scheme Name | Atal Pension Yojana |
| Abbreviation | APY |
| Launch Date | 9 May 2015 |
| Operational Date | 1 June 2015 |
| Administered By | PFRDA |
| Minimum Joining Age | 18 years |
| Maximum Joining Age | 40 years |
| Pension Starting Age | 60 years |
| Minimum Monthly Pension | ₹1,000 |
| Maximum Monthly Pension | ₹5,000 |
| Contribution Frequency | Monthly, Quarterly or Half-Yearly |
| Bank Account | Mandatory |
| Pension Guarantee | Government of India |
| Nomination | Mandatory |
| Maximum Accounts | One per individual |
Important: From 1 October 2022, individuals who are or have been income-tax payers are not eligible to join APY. This restriction applies to new enrollment under the scheme.
2. Atal Pension Yojana Benefits: Why Should You Join?
Atal Pension Yojana provides several benefits to eligible subscribers who want to build a regular retirement income.
Let’s understand its major advantages.
A. Guaranteed Monthly Pension Up to ₹5,000
The most important benefit of APY is the guaranteed minimum monthly pension after the subscriber reaches 60 years of age.
Depending on the selected pension option, subscribers receive:
| Selected Pension | Monthly Amount | Annual Pension |
|---|---|---|
| Option 1 | ₹1,000 | ₹12,000 |
| Option 2 | ₹2,000 | ₹24,000 |
| Option 3 | ₹3,000 | ₹36,000 |
| Option 4 | ₹4,000 | ₹48,000 |
| Option 5 | ₹5,000 | ₹60,000 |
The selected pension is payable for the subscriber’s lifetime, subject to the scheme rules.
B. Government-Guaranteed Minimum Pension
APY provides a defined minimum pension backed by the Government of India.
If the actual investment returns are insufficient to generate the promised minimum pension, the Government will fund the shortfall according to the scheme provisions.
If investment returns are higher than the assumed returns, the subscriber may receive enhanced benefits in accordance with the scheme rules.
C. Financial Security After Retirement
Many people depend entirely on their monthly earnings during their working years.
After retirement, maintaining the same lifestyle can become difficult without a regular source of income.
APY encourages disciplined savings and helps eligible individuals prepare for their retirement years.
D. Spouse Pension Benefit
APY also provides an important benefit to the subscriber’s spouse.
After the death of the subscriber, the spouse is entitled to receive the same monthly pension amount until the spouse’s death.
For example, if the subscriber selected a ₹5,000 monthly pension, the eligible spouse will receive ₹5,000 per month after the subscriber’s death, subject to the scheme rules.
E. Return of Pension Wealth to Nominee
After the death of both the subscriber and the spouse, the nominee becomes eligible to receive the accumulated pension wealth specified under the scheme.
This feature helps provide financial support to the subscriber’s family even after the subscriber and spouse are no longer alive.
F. Flexible Contribution Frequency
Subscribers can choose their contribution frequency from the following options:
Monthly
Quarterly
Half-yearly
The contribution is generally collected automatically from the linked savings bank or post office savings account.
G. Affordable Retirement Planning
People who start APY at an early age can build their pension entitlement through relatively small periodic contributions.
The contribution depends on the selected pension slab and the subscriber’s joining age.
3. Atal Pension Yojana Eligibility Criteria 2026
Before applying for APY, applicants should understand the eligibility requirements.
The following conditions generally apply:
The applicant must be an Indian citizen.
The applicant must be at least 18 years old.
The applicant must not have crossed 40 years of age.
The applicant must have a savings bank account or post office savings bank account.
The applicant must not be or have been an income-tax payer on the date of application.
The applicant must provide the required nomination and other enrollment information.
Important Income Tax Eligibility Rule
From 1 October 2022, individuals who are or have been income-tax payers are not eligible to join APY.
This means that simply being employed in a private company or working in a government organisation does not automatically make someone ineligible.
The relevant restriction is the income-tax payer condition, along with the other scheme requirements.
Can Government Employees Apply for APY?
Yes, eligible Indian citizens working in government organisations or private companies can join APY if they satisfy the applicable eligibility conditions.
The scheme does not automatically exclude a person simply because they are a government employee, private-sector employee or NPS subscriber.
Can a Person Above 40 Years Join APY?
No. A person who has crossed 40 years of age cannot newly enroll under the scheme.
The joining age is between 18 and 40 years.
Can NRIs Apply for Atal Pension Yojana?
APY is available to eligible Indian citizens. An NRI who remains an Indian citizen and meets the prescribed eligibility requirements may enroll through a participating bank.
Can One Person Open Multiple APY Accounts?
No. Only one APY account is permitted per individual.
Multiple APY accounts under different banks are not allowed.
4. Atal Pension Yojana Contribution Chart 2026
The contribution amount is one of the most important things applicants want to know before joining APY.
The monthly contribution depends on:
Age at the time of joining.
Selected monthly pension.
Contribution period until the age of 60.
A person joining at 18 years of age generally contributes less than someone joining at 40 years because the younger subscriber has a longer contribution period.
Monthly Contribution Chart: Joining at 18 Years
| Desired Monthly Pension | Monthly Contribution |
|---|---|
| ₹1,000 | ₹42 |
| ₹2,000 | ₹84 |
| ₹3,000 | ₹126 |
| ₹4,000 | ₹168 |
| ₹5,000 | ₹210 |
Monthly Contribution Chart: Joining at 40 Years
| Desired Monthly Pension | Monthly Contribution |
|---|---|
| ₹1,000 | ₹291 |
| ₹2,000 | ₹582 |
| ₹3,000 | ₹873 |
| ₹4,000 | ₹1,164 |
| ₹5,000 | ₹1,454 |
These figures illustrate the prescribed monthly contribution schedule for the respective joining ages and pension slabs.
Why Should You Join APY Early?
Consider two people who want a pension of ₹5,000 per month.
Person A joins at 18 years and contributes ₹210 monthly.
Person B joins at 40 years and contributes ₹1,454 monthly.
Both select the same pension slab, but their monthly contribution requirements are significantly different.
This demonstrates why starting retirement planning early can make a substantial difference.
Note: These are monthly contribution examples. Quarterly and half-yearly contribution amounts are calculated according to the applicable APY contribution schedule. Always check the official contribution chart before enrollment.
5. How to Apply Online for Atal Pension Yojana 2026?
Many applicants search for Atal Pension Yojana online registration because they want to open an APY account without repeatedly visiting their bank.
The Government provides digital enrollment facilities through the eAPY platform, along with enrollment through participating banks and post offices.
Method 1: Apply Through the Official eAPY Portal
The digital enrollment process generally involves the following steps:
Visit the official APY/eNPS enrollment facility.
Select Atal Pension Yojana.
Provide the required bank and personal information.
Enter your savings bank account details.
Provide your date of birth and other requested information.
Select your preferred monthly pension option.
Choose the contribution frequency.
Enter spouse and nominee details, where applicable.
Provide the required declarations and consent.
Submit the application and complete the verification process.
After successful enrollment, save your acknowledgment and account details.
The availability of digital enrollment and the exact steps may depend on the platform and bank.
Method 2: Apply Through Internet Banking
If your bank provides an APY enrollment facility through internet banking, you may be able to complete the process online.
General steps:
Open your bank’s official website.
Log in to your internet banking account.
Search for Government Schemes or Pension Services.
Select Atal Pension Yojana.
Enter the requested personal information.
Select the desired pension amount.
Provide nominee and spouse details.
Authorize automatic contribution deduction.
Submit the application.
Save the confirmation.
Method 3: Apply Through Mobile Banking
Some participating banks also provide APY enrollment through their official mobile banking applications.
The process generally includes selecting APY, entering personal details, selecting the pension slab and authorizing automatic deductions.
Method 4: Apply Through a Bank Branch or Post Office
Applicants who prefer offline enrollment can visit their participating bank branch or post office.
Request the Atal Pension Yojana registration form, complete the details and submit it along with the required information.
The bank or post office will process the application according to the prescribed enrollment procedure.
6. Documents Required for Atal Pension Yojana
Applicants should keep the following documents and details ready:
Aadhaar card.
Savings bank or post office account details.
Mobile number.
Date of birth and age-related information.
Spouse details, if applicable.
Nominee details.
PAN or other tax-related declarations, where requested.
Completed APY registration form.
Aadhaar may be provided for identification and related services.
The bank may request additional information depending on the enrollment process.
Important: Providing correct spouse and nominee details is essential because these details play an important role in pension continuation and settlement after death.
7. Atal Pension Yojana Contribution Payment and Auto-Debit
After successful enrollment, the subscriber must make regular contributions until reaching 60 years of age.
The contribution is automatically deducted from the linked savings bank or post office account.
Subscribers can select one of three contribution frequencies.
Monthly Contribution
The prescribed contribution is deducted every month.
Quarterly Contribution
The contribution is collected once every quarter.
The quarters are generally:
April to June
July to September
October to December
January to March
Half-Yearly Contribution
Subscribers can also select half-yearly contributions.
The two half-year periods are:
April to September
October to March
The subscriber should maintain sufficient account balance on the applicable deduction date.
What Happens If the APY Contribution Is Delayed?
If sufficient money is not available in the linked account, the contribution may not be deducted successfully.
The subscriber may be required to pay the pending contribution along with applicable overdue interest.
As per the prescribed rules, overdue interest is generally calculated at ₹1 per month for every ₹100 or part thereof of the contribution amount for each delayed monthly contribution.
Repeated defaults can affect the account and lead to continued deduction of applicable account charges.
Therefore, maintaining sufficient bank balance is important.
8. What Happens After Reaching 60 Years Under APY?
Once the subscriber reaches 60 years of age, the pension benefit becomes payable according to the selected pension slab and applicable scheme provisions.
For example:
If a subscriber selected a ₹5,000 monthly pension, the subscriber will receive a minimum monthly pension of ₹5,000 for life.
Similarly, a subscriber who selected ₹3,000 will receive a minimum monthly pension of ₹3,000.
The subscriber needs to submit the prescribed request to the associated bank or post office to begin receiving the pension.
What Happens After the Subscriber’s Death?
The spouse becomes entitled to receive the same monthly pension that the subscriber was receiving.
For example:
If the subscriber received ₹4,000 every month, the eligible spouse will receive ₹4,000 every month after the subscriber’s death, until the spouse’s death.
What Happens After Both Subscriber and Spouse Die?
After the death of both the subscriber and spouse, the nominee becomes eligible to receive the pension wealth accumulated under APY, according to the applicable scheme provisions.
9. What Happens If the Subscriber Dies Before 60 Years?
This is one of the most important questions about Atal Pension Yojana.
If the subscriber dies before reaching 60 years, the scheme provides options for the spouse.
Option 1: Spouse Continues the APY Account
The spouse can choose to continue the APY account for the remaining contribution period, up to the date when the original subscriber would have attained 60 years.
The spouse must continue making the prescribed contributions.
After completion of the contribution period, the spouse becomes entitled to receive the same pension amount as the deceased subscriber, subject to scheme rules.
Option 2: Spouse or Nominee Receives the Accumulated Corpus
Alternatively, the accumulated pension wealth under the APY account can be returned to the spouse or eligible nominee, as applicable.
The family should contact the associated bank or post office to understand the required procedure and submit the necessary documents.
10. Can You Exit Atal Pension Yojana Before 60 Years?
Yes. Voluntary exit from APY before reaching 60 years is permitted under the applicable exit guidelines.
However, the amount payable depends on the subscriber’s circumstances and the relevant scheme rules.
In the case of voluntary exit, the subscriber generally receives their own contributions along with the net actual income earned on those contributions after applicable account maintenance charges.
For subscribers who joined before 31 March 2016 and received Government co-contribution, the Government co-contribution and the income earned on it are not returned upon voluntary exit.
There are also separate provisions for death and specified exceptional circumstances.
Therefore, subscribers should carefully understand the financial implications before requesting early exit.
11. Atal Pension Yojana Tax Benefits
Many applicants also want to know whether contributions made under APY qualify for income-tax benefits.
APY subscribers may be eligible for applicable tax benefits under the relevant provisions of the Income-tax Act.
The tax treatment is subject to the applicable tax regime, eligibility conditions and prevailing tax laws.
Subscribers should consult a qualified tax professional or review the latest Income Tax Department guidance before claiming any deduction.
Remember that individuals who are or have been income-tax payers are not eligible to newly join APY from 1 October 2022.
12. Atal Pension Yojana vs National Pension System (NPS)
Atal Pension Yojana and National Pension System are both retirement-oriented schemes, but they have different features.
| Feature | Atal Pension Yojana | National Pension System |
|---|---|---|
| Main Objective | Guaranteed minimum pension | Long-term retirement investment |
| Joining Age | 18–40 years | Depends on NPS sector and rules |
| Pension Structure | ₹1,000–₹5,000 minimum monthly pension slabs | Depends on accumulated corpus and annuity |
| Government Guarantee | Minimum pension under APY | No general guaranteed pension |
| Contribution | Based on age and pension slab | Based on subscriber’s contribution |
| Taxpayer Eligibility | Income-tax payers cannot newly join | Different eligibility rules |
| Main Target Group | Workers in unorganised sector | Eligible individuals across sectors |
Both schemes serve retirement-planning purposes, but their contribution structures, eligibility conditions and benefits are different.
13. How to Check Atal Pension Yojana Account Status?
After opening an APY account, subscribers should regularly check their contribution details and account status.
You can check APY account information through the following methods:
A. Through Your Bank
Visit the bank branch associated with your APY account and request the latest account details.
B. Through APY Online Services
Use the official APY service facilities to check account information.
Depending on the service available, you may be able to access your account using your PRAN and other required information.
C. Through Transaction Statements
Subscribers can obtain APY transaction statements to review contributions, account balance and other relevant details.
D. Through SMS Notifications
Subscribers may receive SMS updates regarding their APY account and contribution transactions if the registered mobile number is active and linked.
14. Common Mistakes to Avoid While Applying for APY
Many applicants make mistakes during enrollment or while maintaining their APY accounts.
Here are some important points to remember:
Do not enter an incorrect date of birth.
Select the pension amount carefully.
Provide accurate spouse information.
Enter correct nominee details.
Maintain sufficient bank balance for contributions.
Do not open multiple APY accounts.
Understand the income-tax eligibility restriction.
Keep your registered mobile number updated.
Save your PRAN and enrollment acknowledgment.
Check your contribution statements periodically.
These precautions can help avoid unnecessary problems during pension processing.
15. Frequently Asked Questions About Atal Pension Yojana 2026
Q1. What is Atal Pension Yojana?
Atal Pension Yojana is a government-backed pension scheme that provides eligible subscribers with a guaranteed minimum monthly pension of ₹1,000 to ₹5,000 after reaching 60 years of age.
Q2. Who can apply for APY in 2026?
Indian citizens aged 18 to 40 years who satisfy the scheme’s eligibility conditions can apply. Individuals who are or have been income-tax payers are not eligible to newly join from 1 October 2022.
Q3. What is the maximum pension under Atal Pension Yojana?
The maximum guaranteed minimum monthly pension available under APY is ₹5,000.
Q4. What is the minimum monthly contribution under APY?
For a person joining at 18 years, the monthly contribution starts at ₹42 for a selected pension of ₹1,000.
Q5. Can I get ₹5,000 pension after retirement?
Yes. An eligible subscriber who selects the ₹5,000 pension option and completes the prescribed contributions can receive a minimum monthly pension of ₹5,000 after reaching 60 years.
Q6. Can a 45-year-old person apply for APY?
No. The maximum age for new enrollment is 40 years.
Q7. Is APY available for private employees?
Yes. Eligible private-sector employees can join if they satisfy the age, income-tax and other scheme conditions.
Q8. Can government employees join APY?
Yes. Government employment alone does not make a person ineligible. The income-tax payer restriction and other eligibility conditions apply.
Q9. Can an income-tax payer apply for Atal Pension Yojana?
No. An individual who is or has been an income-tax payer on the date of application is not eligible to newly join APY from 1 October 2022.
Q10. Is Aadhaar mandatory for APY?
Aadhaar details may be provided for identification and related services. Check the current enrollment requirements with your participating bank or post office.
Q11. Can I change my pension amount?
The scheme permits eligible subscribers to upgrade or downgrade their pension amount, subject to the prescribed rules and applicable charges.
Q12. What happens if I miss an APY contribution?
Delayed contributions may attract overdue interest. Subscribers should maintain sufficient funds in their linked bank account.
Q13. What happens to APY after the subscriber dies?
The spouse can receive the same monthly pension after the subscriber’s death, subject to scheme rules.
Q14. What happens after the spouse dies?
The nominee becomes eligible to receive the accumulated pension wealth under the scheme.
Q15. Can I withdraw money from APY before 60 years?
Voluntary exit is permitted under applicable rules. However, the amount refunded depends on the subscriber’s contribution history and scheme provisions.
Q16. Is APY a government-guaranteed pension scheme?
Yes. The Government of India guarantees the minimum pension amount specified under the scheme, subject to its conditions.
Q17. Can I open APY through a post office?
Yes. Eligible individuals can enroll through participating post offices.
Q18. Is APY available online?
Yes. Digital enrollment is available through the official eAPY facility, subject to applicable requirements.
Q19. How many APY accounts can one person open?
Only one APY account is permitted per individual.
Q20. When does the APY pension start?
The pension begins after the subscriber reaches 60 years of age and completes the prescribed procedure.
16. Why Is Atal Pension Yojana Important for India’s Future?
India has a large workforce employed in the unorganised sector.
Many workers earn their livelihood through small businesses, agriculture, construction work, street vending, domestic services, transport services and other occupations.
Unlike many formal-sector employees, these workers may not have access to employer-provided retirement benefits.
As people grow older, maintaining a regular source of income becomes increasingly important.
Atal Pension Yojana encourages individuals to develop a habit of regular retirement savings.
Its defined pension slabs and government-backed minimum pension structure make it possible for eligible individuals to plan for a basic level of income after retirement.
The scheme also recognises that retirement security should not be limited to individuals working in large companies or government departments.
By encouraging participation through banks and post offices, APY makes formal pension enrollment accessible to a wider section of society.
However, a pension of ₹5,000 per month may not be sufficient to meet all future living expenses, especially considering inflation.
Therefore, individuals should consider APY as one component of their overall retirement planning and evaluate whether additional savings or retirement investments are required.
Conclusion: Start Planning Your Retirement with Atal Pension Yojana 2026
Atal Pension Yojana is an important government-supported retirement savings initiative that aims to provide financial security during old age.
With a guaranteed minimum monthly pension ranging from ₹1,000 to ₹5,000, the scheme offers eligible Indian citizens an opportunity to prepare for retirement through regular contributions.
The scheme is particularly useful for eligible workers in the unorganised sector who may not have access to a formal pension system.
Its major advantages include government-backed minimum pension, spouse pension benefits, nominee benefits and flexible contribution frequencies.
However, applicants should carefully check the eligibility requirements, contribution chart, tax-related restrictions, withdrawal rules and pension conditions before enrolling.
Starting early can reduce the required monthly contribution for the same selected pension slab.
Remember: Retirement planning should not begin when you stop working. It should begin while you are earning.
If you are eligible, understand the scheme and explore enrollment through your participating bank, post office or the official eAPY portal.
A disciplined saving habit today can help build greater financial independence tomorrow.
Official Website and Important Links
For accurate information, enrollment and scheme updates, refer to the following official resources:
PFRDA Official Website: https://www.pfrda.org.in/
Department of Financial Services: https://financialservices.gov.in/
National Pension System / eNPS Services: https://enps.nsdl.com/
India Post: https://www.indiapost.gov.in/
Official APY Helpline: 1800-110-069
Disclaimer: This article is intended for educational and informational purposes only. Atal Pension Yojana is governed by official scheme rules and PFRDA guidelines. Contribution amounts, eligibility conditions, tax provisions, withdrawal procedures and pension benefits are subject to applicable government notifications and revisions. Please verify the latest details with your bank, post office or PFRDA before making any financial decision.

Comments are closed.